Farm and rural property insurance for working land
A homeowners policy was never meant to cover a tractor, a hay barn or a farm stand. We write coverage that understands how rural Maine properties actually work.
Sample premiums from $138 a month. Sample figures for illustration.
How we approach farm & rural property coverage
Rural properties combine a home with outbuildings, equipment and often a small business. Standard homeowners forms limit or exclude farm property, livestock and liability from selling eggs, produce or maple syrup. A farm and ranch policy, or a homeowners policy with the right farm endorsements, closes those gaps.
We have insured Maine farms since the 1960s. We look at barns and their construction, woodstoves in workshops, farm stand liability, custom farming for neighbors and equipment values, then compare carriers that understand agriculture instead of treating it as an exception.
How a quote comes together
Most farm & rural property quotes take one conversation and a day or two of comparison.
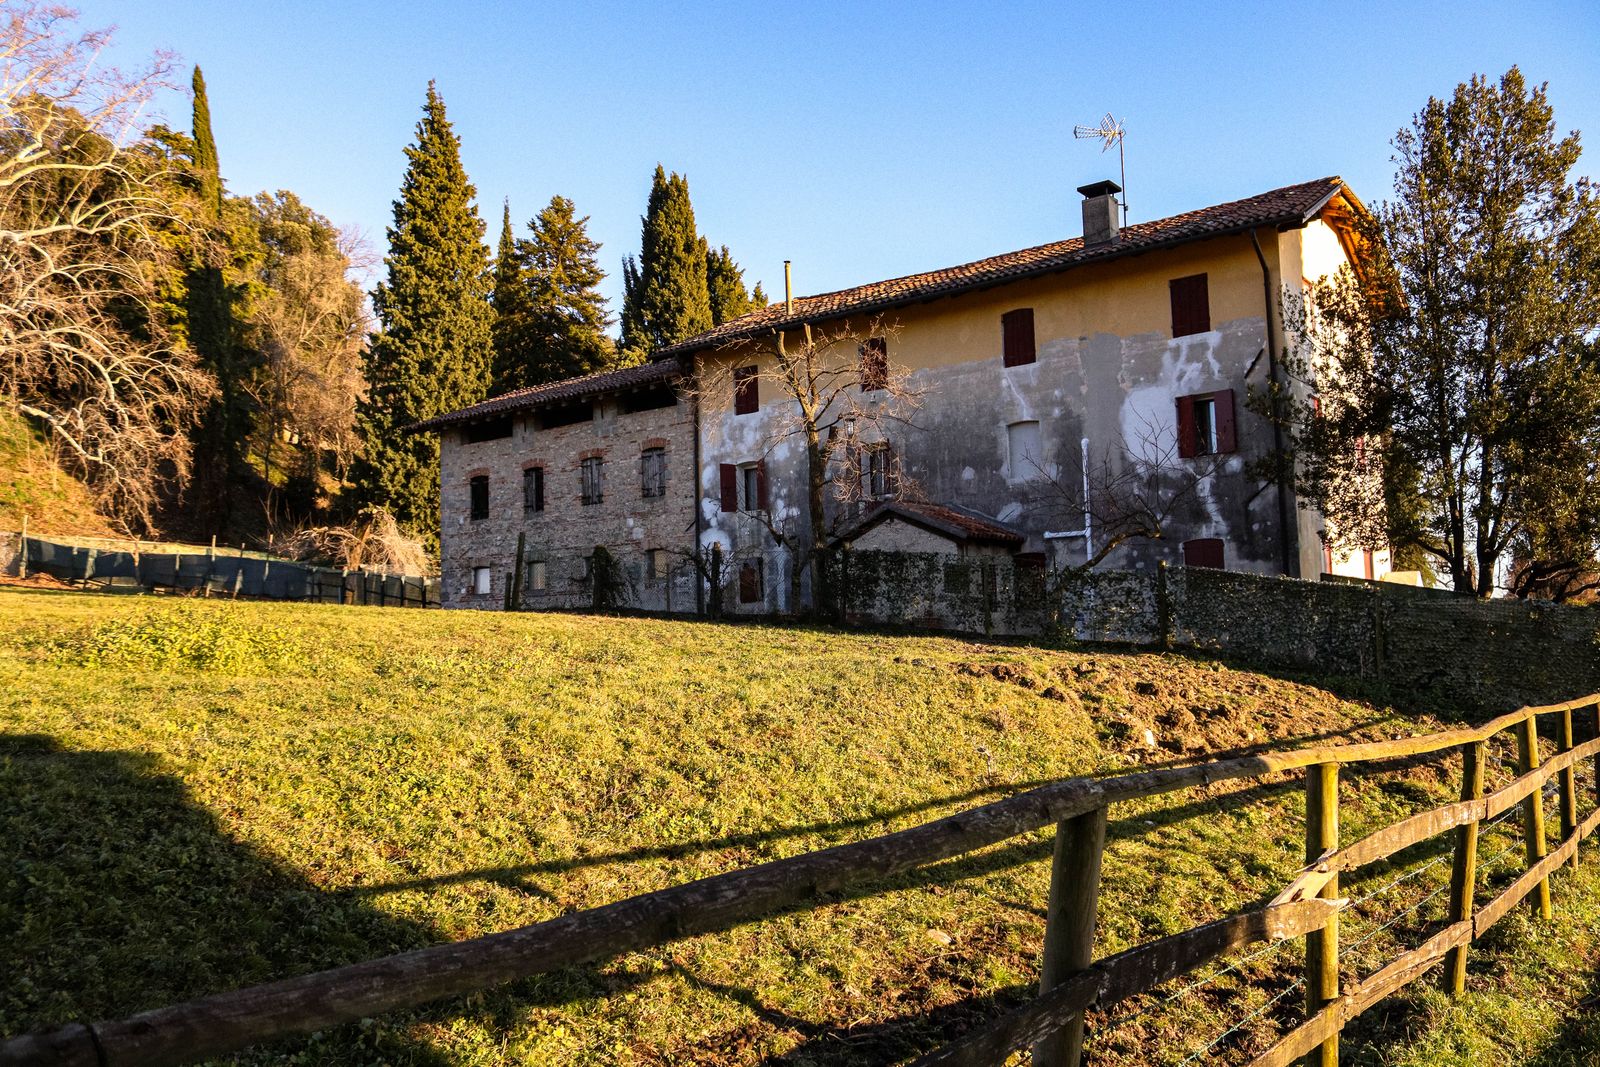
Property walk
We document outbuildings, equipment and how the land is used.
Hobby or commercial
We determine whether a homeowners endorsement or a farm policy fits best.
Value the equipment
Tractors, implements and tools listed at realistic values.
Compare farm markets
Carriers with agricultural programs quote the full property.
What moves the price
These factors carry the most weight with the carriers we represent. We explain each one on your quote.
Outbuilding construction
Older wood barns cost more to insure than steel buildings.
Farm income
Commercial operations need broader liability than hobby farms.
Heating in outbuildings
Woodstoves and heaters in barns and shops increase fire risk.
Distance to fire protection
Rural properties far from a hydrant or station rate higher.
Visitors
Pick-your-own, farm stays and events add liability exposure.
Why neighbors choose an independent agent
- Since the 1960s
- Decades of insuring Maine farms and rural homesteads.
- Right-sized policies
- We avoid paying commercial farm prices for a hobby operation.
- Seasonal adjustments
- Coverage for hay and equipment that changes with the season.
- Agritourism guidance
- Liability planning for farm stands, events and visitors.
Often paired with farm & rural property
All coverage
Homeowners
Dwelling, belongings and liability for the house you live in, priced on what it costs to rebuild in Maine.
Sample premiums from $96 a month
Commercial auto
Pickups, service vans and box trucks that keep your business on the road, from one vehicle to thirty.
Sample premiums from $142 a month per vehicle
Personal umbrella
An extra $1 million or more of liability above your home, auto and boat policies.
Sample premiums from $26 a month for $1M
Farm & rural property questions
Most homeowners policies exclude or strictly limit farming activity. A farm endorsement or policy is usually needed once you sell products.
Farm equipment is best scheduled on a farm policy or inland marine form, with coverage on and off the property.
Standard coverage is for named perils such as fire, lightning and attack by animals. Illness is generally excluded.
Compare farm & rural property quotes in one call
Tell us what you need to protect. A licensed agent on Fore Street shops it, explains it, and sends a clear side-by-side, usually within one business day.
No obligation. Licensed agents. Coverage subject to policy terms.